

The travel accident benefit (a lump sum for accidental death or permanent disablement) pays up to S$675,000 for an accident on a common carrier, meaning a scheduled flight, ferry, train or bus you paid to ride. A lower limit of up to S$202,500 applies to accidents during the rest of the insured journey, once you have left the common carrier. The cover extends to the cardholder, spouse, children and a domestic helper, with sub-limits for family members set out in the summary of cover. All figures shown are Singapore-dollar equivalents, converted from the policy's US dollar limits at about 1.35 and paid in local currency.
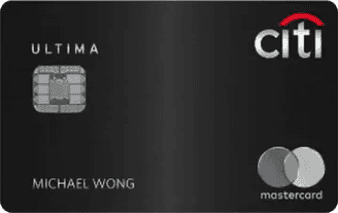
What does the Citi ULTIMA card's complimentary travel insurance actually cover?
Citibank·SGD 4,199/year·Mastercard World Elite·AIG Asia Pacific Insurance
2,9/5Independent review · verified September 2026
3,2
1,0
Our Verdict · Travel Insurance
Our take on travel insurance for the Citibank ULTIMA

Expert review · Pauline LauroreAuthor of HelloSafe's card insurance reviews
The Citi ULTIMA is invite-only and sits at the very top of Citi's Singapore range, so its complimentary travel insurance is the strongest cover Citi offers: the AIG Mastercard World Elite policy at network level, the same master policy that sits behind the Citi Prestige. You get up to S$675,000 in overseas medical expenses, up to S$675,000 for emergency evacuation and return of remains, up to S$675,000 for a common-carrier travel accident (a scheduled flight, ferry, train or bus you paid to ride), up to S$10,125 for trip cancellation, and personal liability abroad up to S$675,000. One point matters before you rely on any figure: the benefit limits are set in US dollars and shown here converted to Singapore dollars at about 1.35, so the exact payout moves with the exchange rate on the day AIG settles. Cover only switches on when the air fare, or the taxes and surcharges on a miles booking, is charged to the card, and COVID-19 handling is not spelled out in the wording, so confirm it with AIG before you travel. This is real travel insurance rather than a token perk, but it is still worth pairing with a standalone policy if you want fixed Singapore-dollar certainty or higher cancellation limits.
What works on travel
- Up to S$675,000 in overseas medical expenses for injury or sickness, among the highest complimentary limits in Singapore
- Up to S$675,000 for emergency medical evacuation and return of mortal remains, arranged by AIG's 24-hour assistance line
- Up to S$10,125 for trip cancellation, with curtailment and postponement each up to S$10,125 as well
- Purchase protection up to S$4,050 per occurrence, plus separate e-commerce cover, which most Singapore cards do not offer
Where travel breaks down
- The benefit limits are set in US dollars and paid in local currency, so the Singapore-dollar figures shown depend on the exchange rate
- The card is invite-only and the annual fee is high, so the cover can never be applied for or treated as free
- COVID-19 handling is not stated in the policy wording and should be confirmed with AIG before travel
- Cover activates only when the air fare, or the taxes on a miles redemption, is charged to the card
Our methodology
Every score is derived from official bank documents: terms and conditions, benefit guides, and claim procedures. No commercial relationship influences our ratings.
Travel Insurance · 14 guarantees
What does Citibank ULTIMA Travel Insurance actually cover?
The S$675,000 headline is the common-carrier accident sum, not the medical limit. It pays a lump sum for death or disablement, not hospital bills.
What's covered
- Accidental death or permanent disablement on a scheduled flight, ferry, train or bus up to S$675,000
- Accidents during the insured journey off the common carrier up to S$202,500
- Cardholder, spouse, children and domestic helper, with family sub-limits
What's not covered
- War, terrorism handling as set out in the policy, nuclear and chemical events
- Self-inflicted injury, suicide and criminal acts
- Hazardous activities such as professional sport, scuba diving and mountain climbing
COVID-19 is not clearly addressed in the policy wording. Until AIG confirms otherwise, do not assume a COVID hospital stay is paid under this S$675,000 benefit.
Break a leg in Bali or land in a Tokyo hospital with appendicitis, and this benefit pays the usual reasonable and customary charges for overseas medical treatment up to S$675,000 per person. It covers both injury and sickness, worldwide, and there is no cap on the number of trips. This is a genuine medical benefit, unlike the token evacuation-only cover on most Singapore cards. Two limits apply: pre-existing conditions are excluded, and the S$675,000 figure is the Singapore-dollar equivalent of the policy's US dollar limit, converted at about 1.35 and paid in local currency. MediShield Life does not cover you outside Singapore, which is why a real overseas medical limit matters.
What's covered
- Overseas medical treatment for injury or sickness up to S$675,000
- Hospital room and board, surgery, physician fees, ambulance and prescribed medicines
- Worldwide cover with no limit on the number of trips
What's not covered
- Pre-existing medical conditions
- Pregnancy and related conditions, elective or cosmetic surgery
- Treatment in your country of residence and hazardous activities
The S$675,000 is a combined limit for both evacuation and return of remains, converted from the policy's US dollar limit at about 1.35 and paid in local currency.
If the local hospital cannot treat you, the policy pays up to S$675,000 to move you to the nearest suitable facility or back home, and the same combined limit covers return of mortal remains if the worst happens. An air ambulance from Bali or Bangkok to Singapore can run S$50,000 to S$120,000, so this is one of the more useful benefits on the card. The evacuation must be ordered and arranged by AIG's Assistance Department, so call the 24-hour line before you move. The S$675,000 limit is shared between evacuation and return of remains, and it is the Singapore-dollar equivalent, converted from the policy's US dollar limit at about 1.35 and paid in local currency.
What's covered
- Emergency medical evacuation to the nearest suitable hospital or home up to S$675,000
- Return of mortal remains, including embalming, cremation, coffin and transport, within the same limit
- Worldwide, arranged by AIG's Assistance Department
What's not covered
- Pre-existing medical conditions
- Transport not authorised by the Assistance Department
- Sanctioned destinations and hazardous activities
Dental treatment is paid only when it results from an accidental injury to sound natural teeth, capped at S$135 per tooth within the medical benefit, not as standalone emergency dental cover.
No overseas emergency dental cover. This benefit is not included with this card. Emergency dental treatment overseas is out of pocket.
What's not covered
- Overseas emergency dental is not a benefit of this card
Spend a night or more in an overseas hospital as an inpatient, and the policy pays a daily cash benefit of S$135 per day per person on top of your medical bills. It is meant for the incidentals of a hospital stay, so the amount is modest. The confinement must be recommended by a physician and must happen outside your country of residence. The S$135 figure is the Singapore-dollar equivalent of the policy's US dollar limit, converted at about 1.35 and paid in local currency, and pre-existing conditions are excluded.
What's covered
- S$135 per day for each day of overseas hospital confinement as an inpatient
- Paid in addition to the medical expenses benefit
- Covers cardholder and eligible family members with sub-limits
What's not covered
- Pre-existing medical conditions
- Hospitalisation in your country of residence
- Pregnancy, routine exams and cosmetic surgery
Trip postponement is paid up to S$10,125 for the administrative cost of pushing a trip back, but the policy pays under only one of cancellation, curtailment or postponement for the same event.
Cancel a prepaid trip because you, a travelling companion or a close family member falls seriously ill, and the policy reimburses your lost, non-refundable travel and accommodation deposits up to S$10,125 per person. The same S$10,125 limit applies to trip curtailment if you have to cut a trip short, and to trip postponement if a major travel event, serious illness or damage to your home forces you to push the trip back. You must have booked and paid before the reason arose, and notify AIG as soon as reasonably possible. The policy pays under only one of cancellation, curtailment or postponement for the same event. All figures shown are Singapore-dollar equivalents, converted from the policy's US dollar limits at about 1.35 and paid in local currency.
What's covered
- Trip cancellation up to S$10,125 per person for non-refundable deposits
- Trip curtailment up to S$10,125 if you cut the trip short
- Trip postponement up to S$10,125 for administrative charges after a major travel event
What's not covered
- Pre-existing medical conditions
- Costs refundable by a hotel, airline or travel agent, or covered by other insurance
- Claims from mental or nervous disorders, alcohol or drug abuse, and pregnancy
If a family emergency or serious illness forces you home before the trip ends, trip curtailment reimburses your unused, non-refundable arrangements and the cost of getting back, up to S$10,125 per person. The return benefit is limited to a one-way economy fare on a scheduled carrier, less any credit from your unused return ticket. Notify AIG as soon as reasonably possible. The S$10,125 limit is the Singapore-dollar equivalent of the policy's US dollar limit, converted at about 1.35 and paid in local currency, and pre-existing conditions are excluded.
What's covered
- Trip curtailment up to S$10,125 per person
- Unused, non-refundable travel and accommodation costs
- One-way economy fare home on a scheduled carrier
What's not covered
- Pre-existing medical conditions
- Claims from mental or nervous disorders, alcohol or drug abuse
- Pregnancy and related conditions
Postponement is handled under the trip inconvenience benefit instead: trip postponement pays up to S$10,125 for the administrative cost of pushing a trip back after a major travel event.
No travel disruption cover. This benefit is not included with this card. Extra accommodation and transport from a trip disruption are the cardholder's responsibility.
What's not covered
- Travel disruption is not a benefit of this card
When your scheduled flight is delayed by at least 4 consecutive hours due to bad weather, a mechanical fault, a strike or air traffic restrictions, the policy pays up to S$675 per person. A 4-hour trigger is strong for a complimentary card benefit, where 6 hours is more common. The delay cannot be one that was made public before you booked. The S$675 limit is the Singapore-dollar equivalent of the policy's US dollar limit, converted at about 1.35 and paid in local currency, and you will need the carrier's written confirmation of the delay and its cause.
What's covered
- Up to S$675 for a delay of 4 hours or more
- Delay caused by weather, mechanical fault, strike or air traffic restrictions
- Covers cardholder and eligible family members with sub-limits
What's not covered
- Delays made public or known to you before you booked the trip
- Delays not certified by the carrier
Miss a connecting flight because your incoming flight was delayed or cancelled, and the policy pays up to S$675 per person to cover the knock-on cost. It is a straightforward benefit for the meals and wait that a missed connection creates. The S$675 limit is the Singapore-dollar equivalent of the policy's US dollar limit, converted at about 1.35 and paid in local currency. Keep your ticket, boarding pass and a letter from the carrier confirming the missed connection.
What's covered
- Up to S$675 if you miss a connecting flight
- Triggered by delay or cancellation of your previous flight
- Covers cardholder and eligible family members with sub-limits
What's not covered
- Amounts already compensated by the airline or another party
- Delays known before departure
Lose your suitcase or have it damaged during a trip, and the policy pays up to S$4,050 for personal baggage, including a laptop computer. A single item, pair or set is capped at S$844, and the laptop limit is S$1,350 for one laptop per trip. Settlements allow for wear and tear and depreciation, though electronics under a year old with receipts are not depreciated. You must report the loss to the police, hotel or carrier within 24 hours. All figures shown are Singapore-dollar equivalents, converted from the policy's US dollar limits at about 1.35 and paid in local currency.
What's covered
- Personal baggage including a laptop up to S$4,050
- Clothing and personal effects lost or damaged during the trip
- Covers cardholder and eligible family members with sub-limits
What's not covered
- Single item, pair or set capped at S$844, laptop capped at S$1,350
- Cash, jewellery, watches and fragile items are limited or excluded
- Mysterious disappearance and property left unattended in a public place
When a common carrier delays or misdirects your checked baggage for more than 4 hours after you arrive, the policy pays up to S$675 per person for the essentials you need to buy while you wait. The 4-hour trigger is faster than most complimentary cards. Baggage delay does not apply in your city of permanent residence. The S$675 limit is the Singapore-dollar equivalent of the policy's US dollar limit, converted at about 1.35 and paid in local currency, and the carrier must certify the delay. If the baggage is later declared lost, any delay payment is deducted from the baggage loss claim.
What's covered
- Up to S$675 for checked baggage delayed more than 4 hours
- Covers essential purchases during the wait
- Covers cardholder and eligible family members with sub-limits
What's not covered
- Delays in your city of permanent residence
- Amounts later claimed under baggage loss for the same event
Have your passport or travel tickets stolen abroad, and the policy pays up to S$675 to replace the documents, plus the extra travel and hotel costs of sorting it out. Lost personal money from robbery, burglary or theft is covered up to S$405 within that limit. The loss must be due to robbery, burglary, theft or a natural disaster and reported to the police within 24 hours. All figures shown are Singapore-dollar equivalents, converted from the policy's US dollar limits at about 1.35 and paid in local currency.
What's covered
- Replacement of lost passports, visas and travel tickets up to S$675
- Additional travel and accommodation to replace documents
- Personal money up to S$405 within the S$675 limit
What's not covered
- Shortage due to exchange rate or depreciation
- Travellers cheques not reported to the issuing authority
- Documents lost through your own carelessness
Personal liability (your legal responsibility if you accidentally injure someone or damage their property abroad) is covered up to S$675,000. Knock over an expensive display, or injure another guest in an accident, and this benefit meets the third-party claim and defence within the limit. It applies during the covered trip. The S$675,000 figure is the Singapore-dollar equivalent of the policy's US dollar limit, converted at about 1.35 and paid in local currency. You must not admit fault or settle without AIG's written approval.
What's covered
- Legal liability for accidental injury to a third party up to S$675,000
- Accidental loss of or damage to third-party property
- Defence costs within the limit
What's not covered
- Liability to family, employers or employees
- Liability from vehicles, aircraft, watercraft, firearms or animals
- Liability from any trade, business, profession or criminal act
Policy document
We source benefits from official card guides, but PDFs are sometimes hard to obtain or update. Spotted something off?
Coverage Radar
Where the Citibank ULTIMA wins, where it loses
Coverage snapshot for this tab — click any layer to highlight its scores.
Medical repatriation: well above the market average
Medical fees abroad: above the market average
Hospital cash allowance: above the market average
Overseas emergency dental: not covered by this card
Compare
ULTIMAThis card2.9/5?
SGD 4,199/yrWith travel insuranceIdeal
Complete coverage · 5.0 / 5Premium card avg.
SGD 215 avg. annual feeClick a layer to highlight its scores on the radar.
Side-by-side comparison
How the Citibank ULTIMA stacks up against the alternatives
Same 5 coverage dimensions, ranked head-to-head against the cards most ULTIMA shoppers also consider.
| Card | This card ULTIMA Citibank · SGD 4,199/yr 2.9/5? | Prestige Citibank · SGD 652/yr 2.9/5? | TravelOne HSBC · SGD 196/yr 1.7/5? | |
|---|---|---|---|---|
Trip cancellation Per person, per trip cap | S$10,125 per person Up to S$10,125 | S$10,125 per person Up to S$10,125 | S$1,500 per person Capped S$1,500 | |
Emergency medical Hospital bills abroad | S$675,000 S$675,000 overseas medical | S$675,000 S$675,000 overseas medical | S$150,000 Capped S$150,000 | |
Emergency evacuation Air ambulance + repatriation | S$675,000 S$675,000 evacuation | S$675,000 S$675,000 evacuation | S$1,000,000 Up to S$1,000,000 | |
Trip delay trigger Hours before benefits kick in | 4h / S$675 Trigger: 4 hours | 4h / S$675 Trigger: 4 hours | 8h / S$150 Trigger: 8 hours | |
Trip interruption Covered amount | Not covered Cover this gap → | Not covered | Not covered |
StrongLimited / misleadingNot covered
Data verified against each card's Guide to Benefits, May 2026.
Cardholder reviews
What cardholders say about the Citibank ULTIMA
Cardholder experience with the card, drawn from reviews across Citi's premium range as the invite-only ULTIMA has no separate public reviews 3 reviews
MO
Man of the Hour (Seedly)
Worth it if you can pay the fee
If you can't afford to pay the annual fee then this card isn't for you. Otherwise it's a 5/5 for the benefits and miles it provides.
ET
E T (Seedly)
Useful for travel, no fee waiver
Almost impossible to get a fee waiver for this card, but they do give miles for fee payment. Useful for travel (four night free, unlimited lounge visits)!
S(
Sarah (Seedly)
Concierge made a simple booking hard
Concierge team is the worst! A simple hotel booking became such a complicated process... They're making it difficult for you to get the free 4th night stay.
Emergency · Card assistance line
How to contact Citibank ULTIMA assistance?
AIG claims (Singapore)
+65 6419 1667
8:30am to 5:30pm, Mon to Fri
AIG 24-hour Assistance Department
001 817 826 7014 (call collect outside North America); 866 273 9079 (toll free within North America)
Call collect where outside North America · 24/7
Benefit administrator: AIG Asia Pacific Insurance (AIG Singapore) for Mastercard World Elite
Claims & pre-authorizations
How to make a Citi ULTIMA travel insurance claim
1
Step 1: Call the AIG Assistance Department before any evacuation
For a medical emergency overseas, call AIG's 24-hour Assistance Department before arranging transport: 001 817 826 7014 call collect from outside North America, or 866 273 9079 toll free within North America. An emergency evacuation must be ordered and arranged by the Assistance Department, so calling first is a condition of the S$675,000 evacuation benefit.
2
Step 2: Notify AIG within the deadline and gather your documents
Give written notice of a travel claim within 90 days of the loss, or 30 days for a purchase protection claim. File at https://sg.mycardbenefits.com or contact AIG Asia Pacific Insurance, 78 Shenton Way #09-16, Singapore 079120, tel +65 6419 1667, email APAC.Mastercard@aig.com. Collect itemised bills, any police or carrier report, boarding passes and the card statement.
3
Step 3: Prove the fare was charged to the card, then escalate if needed
Include transaction verification showing the full common-carrier fare, or the taxes and surcharges on a miles booking, was charged to the card, along with copies of the ticket and receipts. If a fair claim is denied and you disagree, you can escalate free of charge to FIDReC, the Financial Industry Disputes Resolution Centre, within 6 months of AIG's final reply.
FAQ
What people ask about the Citibank ULTIMA
- The travel cover switches on when the air tickets for your trip are paid with the Citi ULTIMA card. If you book on frequent-flyer miles instead, the cover still applies as long as the taxes and surcharges are charged to the card. Holding the card alone is not enough, and there is no spend threshold: it is the common-carrier fare, or the taxes on a miles redemption, that triggers the policy. Keep the card statement and the ticket, because a claim needs transaction verification that the fare was charged to the card. If neither the fare nor the taxes touch the card, you travel with no cover under this policy.
- Yes. Overseas medical expenses for injury or sickness are covered up to S$675,000 per person, worldwide and with no limit on the number of trips, which matters because MediShield Life does not cover you outside Singapore. Emergency medical evacuation and return of mortal remains share a combined limit of up to S$675,000, arranged by AIG's 24-hour Assistance Department, which must order the evacuation for it to be paid. A daily in-hospital cash benefit adds S$135 per day during an overseas hospital stay. Pre-existing conditions are excluded. Every figure shown is the Singapore-dollar equivalent, converted from the policy's US dollar limits at about 1.35 and paid in local currency.
- Yes. Cancel a prepaid trip because you, a travelling companion or a close family member falls seriously ill, dies or is injured, and the policy reimburses your lost, non-refundable travel and accommodation deposits up to S$10,125 per person. The same S$10,125 limit applies to trip curtailment if you have to cut a trip short, and to trip postponement if a major travel event forces you to push the trip back. You must have booked and paid before the reason arose, and the fare, or the taxes on a miles booking, must have been charged to the card. The policy pays under only one of cancellation, curtailment or postponement for the same event. Every figure is the Singapore-dollar equivalent of a US dollar limit, converted at about 1.35 and paid in local currency.
- The policy wording does not clearly cover COVID-19, so treat it as not covered under this card until AIG confirms otherwise. There is no explicit COVID-19 medical or cancellation benefit in the document, and a pandemic appears only as a possible trigger for trip postponement, not as medical cover. Pre-existing conditions are excluded throughout. This position is card-specific, so never assume COVID handling carries from one card or insurer to another. If COVID-19 protection matters for your trip, confirm it in writing with AIG on +65 6419 1667, or buy a standalone Singapore travel policy that states COVID-19 medical and cancellation cover clearly.
- The AIG Mastercard World Elite policy sets every benefit limit in US dollars, then pays claims in local currency using the exchange rate on the day the claim is settled. To make the cover easy to read, the limits on this page are shown as Singapore-dollar equivalents, converted at about 1.35, so US$500,000 of overseas medical appears as S$675,000 and US$7,500 of trip cancellation appears as S$10,125. Because the underlying limits are in US dollars, the exact Singapore-dollar payout you receive will move with the exchange rate and may differ slightly from the figures shown. If you want cover stated and paid in fixed Singapore dollars, a standalone Singapore travel policy gives you that certainty.
- Yes. Personal liability, which is your legal responsibility if you accidentally injure someone or damage their property while travelling, is covered up to S$675,000. Knock over an expensive display or injure another guest in an accident, and the policy meets the third-party claim and the defence costs within that limit. It applies during a covered trip whose fare, or miles taxes, was charged to the card. You must not admit fault or agree a settlement without AIG's written approval, as doing so can void the claim. Liability to your own family or employees, and anything arising from vehicles, watercraft, firearms or a business, is excluded. The S$675,000 figure is the Singapore-dollar equivalent of the policy's US dollar limit, converted at about 1.35 and paid in local currency.
- Claims run through AIG Asia Pacific Insurance, the underwriter. File online at https://sg.mycardbenefits.com or contact AIG at 78 Shenton Way #09-16, Singapore 079120, on +65 6419 1667 or APAC.Mastercard@aig.com. Give written notice within 90 days of the loss for a travel claim, or 30 days for purchase protection. For a medical emergency, call the 24-hour Assistance Department before arranging any evacuation. Keep itemised bills, police or carrier reports, boarding passes, and the card statement proving the fare was charged. If AIG denies a claim you believe is fair, you can escalate free of charge to FIDReC, the Financial Industry Disputes Resolution Centre, within 6 months of the final reply.
- Yes. Each covered trip is insured from the departure date to the return date shown on the ticket you charged to the card, up to a maximum of 180 days per trip. There is no limit on the number of trips in a year, so frequent travellers are covered on each journey as long as the fare, or the taxes on a miles booking, is charged to the card. If you are still in hospital or under quarantine on your original return date, the cover extends automatically for up to 30 more days. A trip longer than 180 days falls outside the policy, so a separate annual or long-stay travel policy is the safer choice for extended trips.
- Yes, and it is genuine, unlike most Singapore cards. Items bought entirely on the card are covered against theft or accidental damage within 180 days of purchase, up to S$4,050 per occurrence and a S$27,000 annual aggregate. Gifts and internet purchases count, and nothing needs to be registered. A separate e-commerce purchase protection pays up to S$1,350 for online orders that are not delivered or arrive damaged. For a theft claim you need a police report within 90 days and written notice within 30 days of the loss. What the card does not add is extended warranty, price protection or return protection. All figures shown are Singapore-dollar equivalents, converted from the policy's US dollar limits at about 1.35 and paid in local currency.
- Less so than with most cards, because this is real cover: up to S$675,000 in overseas medical, up to S$675,000 for evacuation, and up to S$10,125 for cancellation. Even so, there are gaps worth closing. COVID-19 handling is not clear, the cover only activates when the fare or the miles taxes hit the card, and the benefit limits are set in US dollars, so the Singapore-dollar figures shown depend on the exchange rate. If you sometimes book on miles without charging the taxes, or you want certain COVID-19 medical and cancellation cover, a standalone Singapore travel policy from around S$20 for a single trip fills those gaps. Treat the card as strong primary cover, and confirm the activation and COVID points before you rely on it alone.
Not just Citibank
Other cards worth considering
ULTIMA is a strong choice — but depending on what you prioritize, one of these may suit you better.
Prestige
Citibank

TravelOne
HSBC
Metal
Revolut
Visa Infinite
Standard Chartered
Fill the gaps in your card
Find complementary travel insurance
We analyze the gaps in your card and recommend the best complementary travel insurance based on your destination and profile.
Step 1 of 3